A busy market doesn’t always mean stronger returns. Assessing the seasonality of rental demand is one way to understand how changing demand, local...

A busy market doesn’t always mean stronger returns. Assessing the seasonality of rental demand is one way to understand how changing demand, local events and property booking patterns may affect London property investment. A considered outlook weighs potential occupancy against the value of each booking.
It makes sense to expect rental demand to shift around holidays and major events, and to want investment decisions based on more than guesswork. This guide explains how seasonality can affect rates and minimum stays, why London’s local calendar matters, and how booking data can help inform an outlook.
A considered strategy treats peak periods differently from quieter weeks while accounting for each property’s location and rental model. The aim is a measured view of market conditions that suits the home, not a blanket assumption that demand will always rise.
Key Takeaways
- Segment properties by location and rental model so seasonal pricing reflects the demand each home is likely to attract.
- Balance occupancy and nightly rates across peak, shoulder and quieter periods instead of relying on a fixed year-round price.
- Factor local events and holidays into pricing and minimum stays, while keeping each property’s booking pattern in view.
- Use booking pace, occupancy and past performance to inform rate changes, rather than reacting to a single busy date.
- During high season, align minimum stays with demand and booking windows to support a considered balance between revenue and occupancy.
1. Portfolio segmentation by location and investment potential
A London property portfolio rarely follows a single investment pattern. Group properties by location, type and investment strategy, then compare their performance within each group. An apartment near major offices may appeal to renters working nearby, while a family home may attract households looking for space. These differences help investors assess each property on its own merits instead of applying one strategy across every asset.
Rental income and potential capital growth are distinct considerations when investing in UK property. A property’s location, type and price can affect its rental prospects, while future growth is not guaranteed. When reviewing an investment, assess its expected income alongside the purchase costs and the investor’s timeframe. The property’s circumstances and applicable rules also matter, so distinguish market expectations from confirmed returns.
No single London area offers the strongest investment potential for every property type and timeframe. Prospects vary with local employers, universities, transport links and visitor attractions. A home near a university, for example, may appeal to renters connected with the institution, while one near a business district may attract professionals. Compare relevant local conditions for each location before deciding where to invest.
Universities, corporate relocations and tourism can influence rental demand in different ways. Term dates may affect student searches near campuses, while job moves can bring interest around employment hubs. Tourism and events may attract renters to well-connected central locations. Before assessing a property’s rental prospects, consider its likely audience, competing availability and the demand drivers in its area.
Investment markets vary by location, so patterns observed in one city should not automatically be applied to another. An investor comparing different areas can consider local demand, property types and the intended rental model. The same principle applies within London: group properties according to the local factors that are relevant to their investment potential rather than assuming every area will perform alike.
Rental demand can change over time, so a flexible investment strategy may help owners respond to changing circumstances. When reviewing a property, consider the likely renter, suitable tenancy arrangements and the investor’s plans for the asset. A renter moving for work, for example, may have different requirements from a household seeking a longer-term home. Any tenancy decisions should also reflect the agreement and applicable rules.
Local conditions can influence demand in particular areas. Identify relevant employers, institutions, transport links and attractions, then review how they relate to the property’s likely audience. Compare the property with nearby options and assess its prospects in context. Investment decisions should be based on relevant evidence rather than an assumption that every location or property type will respond in the same way.
In practice, assessing London property investment starts with a clear view of the portfolio. Group comparable homes, review the demand drivers and investment prospects for each group, and revisit the assessment as circumstances change. This avoids treating one property’s performance as proof that every London asset needs the same pricing or investment strategy.
No single London area offers the strongest investment potential across every property type and timeframe. Rental prospects may be influenced by universities, employment hubs and well-connected central locations, while capital growth is not guaranteed and should be considered separately from rental income.
2. Rental yields and capital growth in London property investment
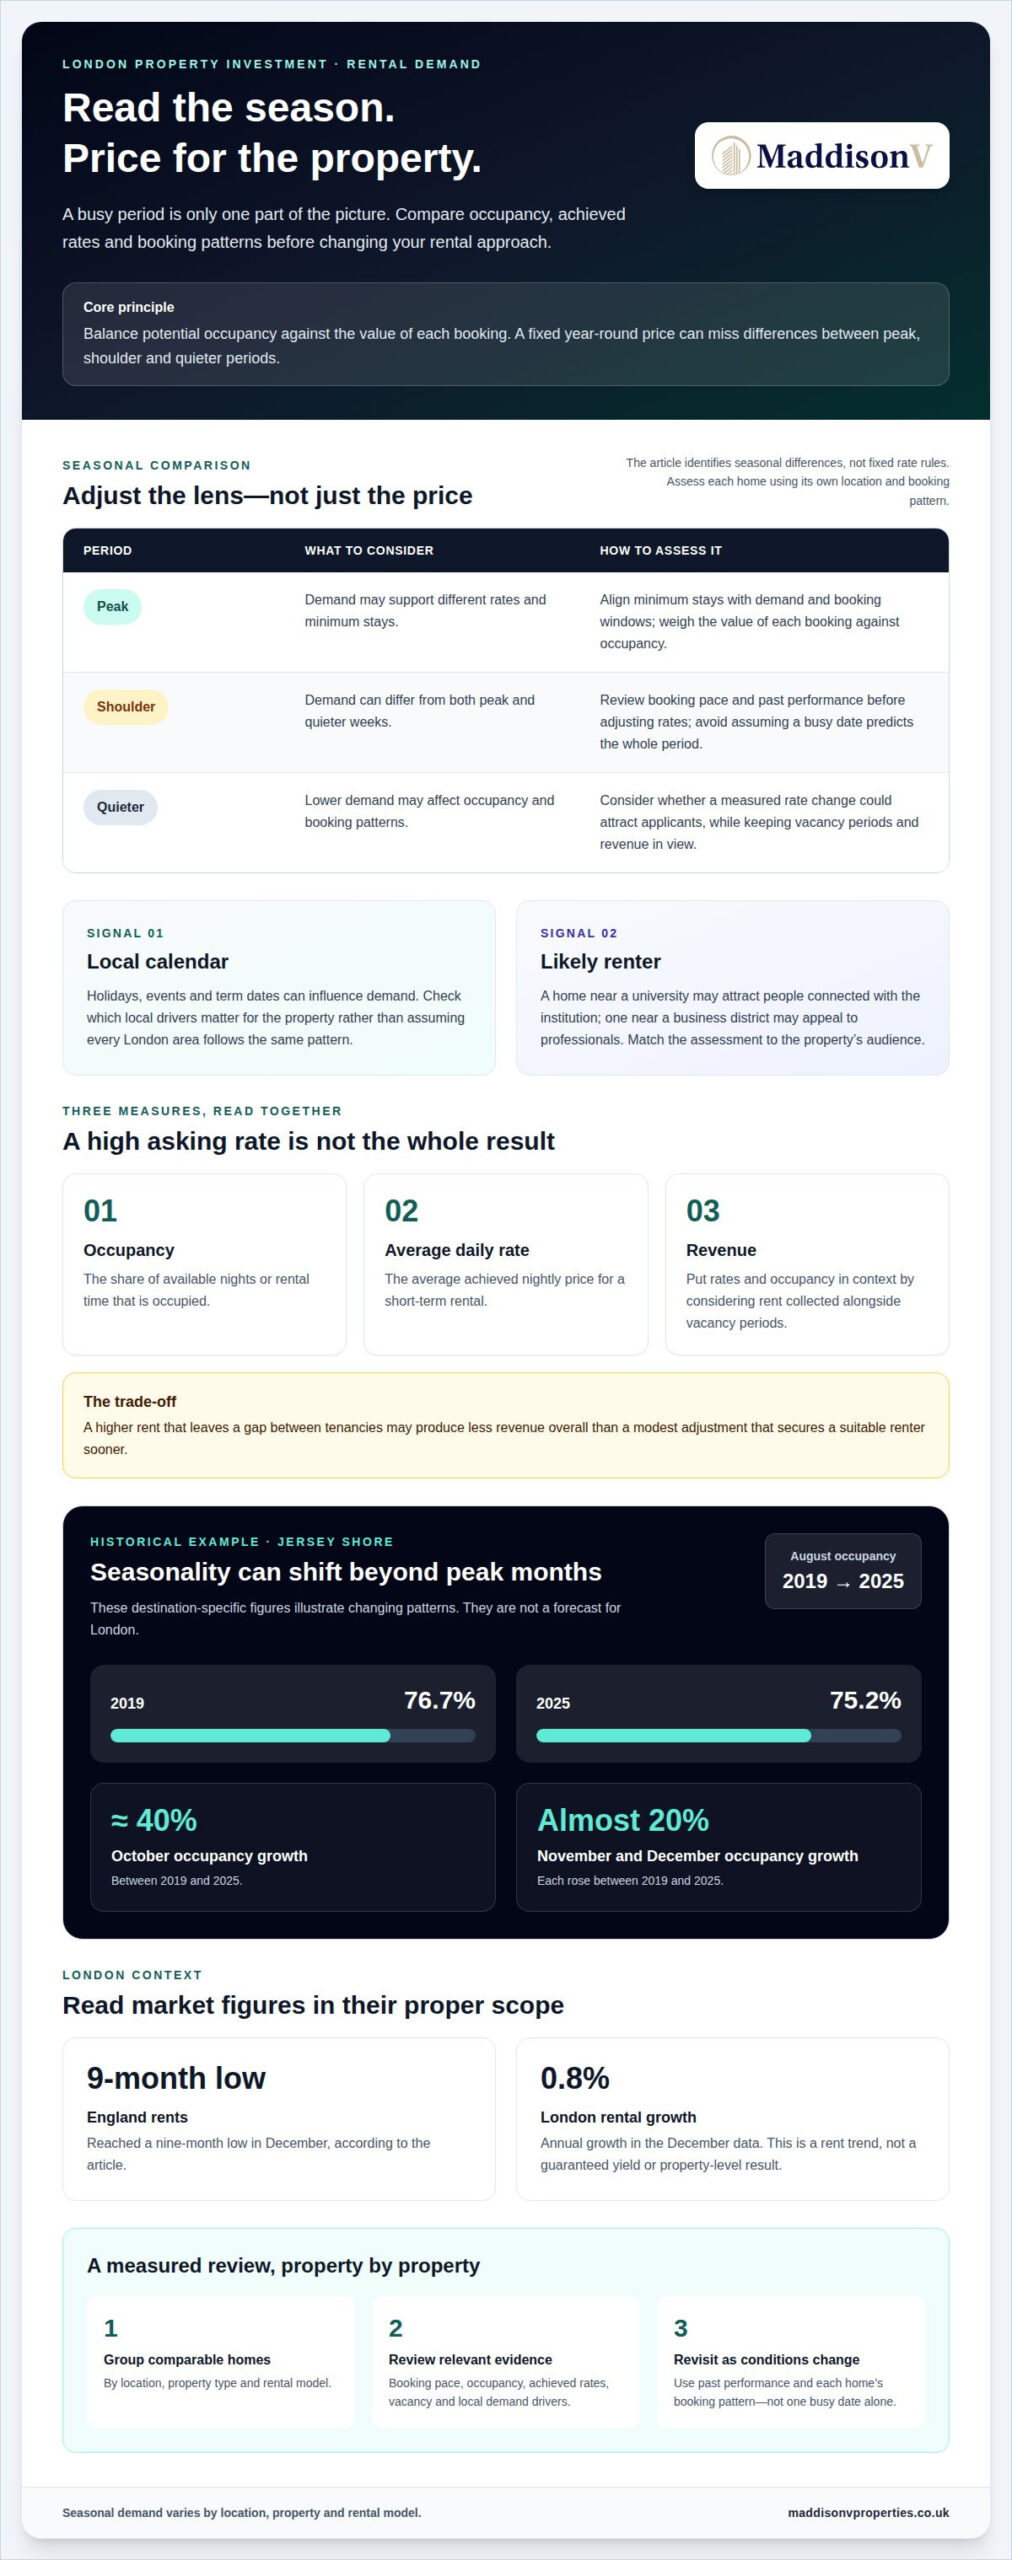
Rental income and potential capital growth are two factors to consider when assessing London property investment. In December, England rents reached a nine-month low, while London rental growth was 0.8% annually in the December data. These figures describe rent trends; they do not guarantee a particular yield or future performance for every property.
Rental demand and achievable rents vary by property and renter profile, so there is no reliable pattern that applies to every London neighbourhood. Compare enquiry volume, viewing activity, achieved rent and vacancy periods for relevant properties. If a property receives fewer enquiries, a measured adjustment to the asking rent may attract applicants. A well-positioned home with steady interest may need no change.
When assessing an investment, consider whether demand supports the asking rent and how long the property may remain vacant. A higher rent that leaves a gap between tenancies may produce less revenue overall than a modest adjustment that secures a suitable renter sooner. Weigh rental income against vacancy risk rather than treating a high asking rent as a guarantee of stronger returns.
Vacation rentals show why occupancy and nightly rates need to be read together. Jersey Shore occupancy in August was 76.7% in 2019 and 75.2% in 2025. Yet shoulder-season demand changed: October occupancy grew by approximately 40% between 2019 and 2025, while November and December occupancy each rose by almost 20%. Those destination-specific patterns aren’t a forecast for London, but they illustrate why owners should assess the evidence for each market rather than assume demand stays unchanged.
Three measures can help clarify property performance. Occupancy shows the share of available nights or rental time that is occupied. Average daily rate measures the average achieved nightly price for a short-term rental. Revenue puts both in context: compare rent collected with vacancy periods rather than treating a high rate as success on its own.
To assess rental income alongside potential capital growth, weigh current enquiries, the property’s historical patterns and the likely cost of an empty period. For a resident approaching renewal, a considered offer may support retention; for a vacant home, a competitive rent may attract a suitable applicant. The right approach depends on the property’s audience and the strength of demand.
Investment decisions are easier to review when performance is compared over time. A property manager can compare occupancy and achieved rates across equivalent periods, then refine the approach as new booking or letting data arrives. Owners seeking coordinated oversight of these decisions can explore professional property management for their London rental portfolio.
3. Assessing London property investment opportunities
London property investment decisions should reflect the location, property type and investor’s objectives. Compare relevant market information with the property’s characteristics and intended holding period. Purchase price, expected rental income and potential costs are useful considerations, but no single indicator guarantees a particular return. The key question is whether the investment suits your plans and risk tolerance.
For each property, compare its asking price and rental prospects with similar nearby homes. Consider whether the expected income supports your objectives after costs, and whether the property’s features are likely to appeal to prospective tenants. If the figures do not meet your requirements, reassess the price or consider other opportunities. This approach bases decisions on evidence rather than assumptions about future performance.
Location matters as much as the property itself. Review local amenities, transport connections and the type of demand that may suit the area. A tenant seeking a central base may have different priorities from a family looking for more space. Property condition, size and likely audience all affect how a location may fit an investment strategy.
Investment performance can vary by area and property type. Rental income, purchase costs and potential changes in value should be considered together, rather than relying on one measure alone. London properties do not necessarily share the same prospects. Use relevant local information to compare opportunities and identify which properties suit your investment goals.
Holding period can influence how an investment is assessed. A property intended for long-term ownership may be considered differently from one with a shorter planned holding period. Weigh expected rental income, ongoing costs and potential sale considerations across the full period. A headline yield does not tell the whole investment story.
Tax and legal requirements belong alongside financial assessments. Before proceeding, review applicable property taxes, ownership arrangements and obligations as an overseas buyer. These considerations can affect how a property is acquired and managed, so address them as part of the investment decision.
After purchase, review rental income, costs and property performance against your original expectations. Changes in circumstances or local conditions may affect whether the investment continues to suit your plans. Regular reviews help distinguish longer-term patterns from short-term changes and support informed decisions about the property.
Well-structured investment planning brings the location, property, finances and ownership considerations into one decision process. For London investors, the aim is to assess each opportunity without assuming all areas or properties will perform alike. A tailored review of the property, rental prospects and investment objectives supports more considered decisions.
4. Analyzing property data before adjusting investment plans
Investment decisions should follow evidence, not one busy weekend. Review property performance throughout the year, comparing enquiry volume, time to let, achieved rents and vacancy periods. For a London property, compare summer results with quieter months while keeping property type and location consistent. This helps distinguish a seasonal shift from a change affecting only one property.
Useful data sources include letting history, occupancy records, rental enquiries, comparable market rates and local demand patterns. Property management platforms may combine market data, competitor rates and rental activity, then suggest adjustments. Use these tools to inform decisions, while assessing whether a suggestion suits the property, its audience and the dates being considered.
For short-term rentals, a manager can map revenue per available rental night across all 12 months. This reveals whether a seasonal pattern repeats or whether an apparent peak came from a particular event. For longer-term lets, the review can focus on achieved rents, time to let, renewal outcomes and void periods. These measures answer different questions, so they shouldn’t be treated as interchangeable.
A useful comparison starts with like-for-like periods. Compare the same property’s summer letting pace with its performance in earlier summers, then look at similar homes in the same area. Fewer reservations in a given month may reflect a later booking window rather than weaker demand. Checking lead times alongside occupancy helps prevent an early snapshot from prompting an unnecessary change to an investment plan.
Void periods add another signal. Average rental void periods increased from 23 to 26 days in the January market update. That movement makes vacancy duration worth tracking alongside asking rent, but it doesn’t explain an individual property’s result by itself. An investor also considers location, condition, listing presentation, renter profile and the timing of the vacancy before reviewing a property’s performance.
For example, a short-term property with 30 available nights in a month can be assessed by comparing its booked nights, nightly rate and resulting revenue. If a lower rate attracts additional bookings, the owner weighs the added occupancy against the reduced rate. The strongest outcome is not necessarily the highest nightly figure; it is the pricing pattern that supports overall performance.
Analysis should continue after an investment decision. A 90-day planning period can help identify opportunities for an underperforming property and track whether adjustments correspond with improved results. The owner records the decision, monitors subsequent bookings and compares them with the original pattern. This makes future planning more consistent, particularly when demand shifts between summer, shoulder periods and winter.
No single data source captures every factor in a London property investment decision. Bring together letting records, comparable rates, enquiry trends and local event dates, then review the evidence regularly. This measured process gives owners a clearer basis for decisions and avoids treating automated suggestions as a substitute for property-level judgement.
5. Buying a New Build in London
Buying a new build in London calls for more than comparing the advertised price. Consider the property’s location, layout and intended use, alongside the development’s features and the costs involved. For buyers considering London property investment, the right choice depends on how the home fits their plans, whether for personal use or as a rental.
Review the purchase details before committing. Check what is included in the asking price, the expected completion timing and any relevant charges. Compare properties in the same area and consider how their features and condition meet your requirements. A careful comparison can help you assess whether a particular new build suits your budget and plans.
Think about how the property may work as a home. Layout, storage and access to local amenities can affect its appeal to future residents. If you plan to rent it out, consider the type of tenant the property may suit and whether its features meet likely renter needs.
Price and potential rental performance must be considered together. A new build’s advertised price alone does not show whether it will suit your investment plans. Assess the purchase costs alongside expected rental income and the possibility of periods without a tenant.
Property management can help owners respond to changing rental demand, but recommendations need context. Short-term rental properties using dynamic pricing typically achieve 10-25% higher revenue than properties using static pricing. That market figure isn’t a promise for an individual property. A manager considers booking history, competing availability, event dates and the remaining time before arrival before accepting a rate suggestion.
The same care applies when choosing a rental approach. Consider whether the property suits short-term or longer-term letting, then weigh the proposed rent against expected vacancy and renter demand. Do not assume that a short-term nightly-rate strategy directly applies to a longer-term tenancy.
Reviewing the property and its performance over time can help inform future decisions. Compare achieved rates, booked nights and gaps across similar periods. If a two-night minimum repeatedly fragments availability, a different rule may suit future event periods. If longer stays leave dates unsold, a more flexible approach may attract guests and support revenue.
For owners seeking expert oversight of rental decisions, discuss tailored property management for a London rental.
MaddisonV Properties
MaddisonV Properties helps investors consider London property investment opportunities, rental performance and portfolio priorities as part of a tailored approach. Its Property Management and Portfolio Management services support owners reviewing how their properties fit their longer-term investment plans. This can be particularly useful when a portfolio spans different locations or rental profiles, since one investment approach may not suit every property.
For investors considering a new London property, Property Sourcing can help align property choices with their objectives from the outset. A clear understanding of the asset, intended rental model and local market provides a stronger basis for future decisions.
Contact MaddisonV Properties to discuss your London property requirements.
Build a London property investment strategy
A London property investment strategy should adapt as your objectives and portfolio evolve. Treat each purchase as an ongoing investment decision, not a set-and-forget choice. A disciplined approach to London property investment helps owners make deliberate choices while keeping each property’s long-term role in view.
The next step is to decide what successful performance means for your property: long-term growth, rental income, or a balance that supports your wider investment plans. Clear priorities make it easier to assess future opportunities and avoid reacting to every shift in the market. They also give property discussions a more useful starting point.
MaddisonV Properties can help owners consider investment opportunities alongside their broader property objectives through tailored advice and management support. Discuss your London property investment plans with MaddisonV Properties and take the next step with clarity and confidence.
Frequently Asked Questions
What should UAE investors consider before making a UK property investment?
UAE investors should compare potential rental yields and capital growth across suitable locations, and consider how currency movements may affect their purchase and returns. Tax considerations and the costs of buying and owning a property are also relevant. Reviewing these factors together can help investors assess whether a particular opportunity fits their objectives. For advice on individual circumstances, consult qualified property, tax and legal professionals before proceeding.
How can UAE investors compare London property investment locations?
Compare areas such as Canary Wharf, Nine Elms, Battersea and Westminster based on their suitability for your investment objectives. Consider the property type, expected rental demand, potential yield and prospects for capital growth, rather than assuming one location will perform best in every case. Exchange rates and tax considerations may also affect the overall assessment of a London property investment.

Sign Up Now
Want to read more great articles and blogs subscribe to our newsletter